
See the years ahead.
Follow projected balances, income and spending year by year.
Year-by-year projectionsSMART PLANNING. CONFIDENT FUTURE.
From building wealth to planning retirement, see how today’s choices could shape your future.
Free during closed beta · No credit card required
A beta code is required during closed beta.
MORE CLARITY. BETTER QUESTIONS.
Less guesswork. More perspective.
Explore the moving parts of your plan without losing sight of the bigger picture.
Follow projected balances, income and spending year by year.
Year-by-year projectionsExplore withdrawal and Roth conversion strategies side by side.
Strategy comparisonsSee how different assumptions and simulated market paths may affect your plan.
Monte Carlo simulationsUnderstand modeled taxes, required distributions and Medicare premium impacts.
Tax, RMD & IRMAA insightsONE PLAN THAT GROWS WITH YOU
Bring your accounts, income and spending together. Explore how withdrawals, taxes and timing could affect the years ahead.
THE QUESTIONS WORTH ASKING
Change the assumptions. Compare the possibilities.
Make your next decision with more context.
BUILT AROUND REAL LIFE
You don’t need to have every answer.
You need a useful place to start.
Young professionals can explore contributions, growth assumptions and longer-term goals.
Explore Build WealthCompare retirement timing, income sources and the trade-offs that matter to you.
Explore Retirement PlannerReview spending, withdrawal choices and modeled taxes as your needs evolve.
Explore Retirement PlannerFREE BETA · FUTURE PLAN PREVIEW
Current beta access is free with a valid beta code.
The planned prices below are not available to purchase.
Planned Monthly
A proposed option for flexible access.
Planned Annual
A proposed option for a year of planning.
Planned Founding Member
A proposed one-time access option.
This preview does not promise Lifetime Access. See current beta terms (opens in a new tab).
Planned pricing and features may change before launch. Beta access has no fourteen-day expiration clock and never turns automatically into a paid plan.
A LITTLE MORE CONTEXT
Understand what NestMint does
before you start exploring.
No. Build Wealth helps you explore saving and accumulation. Retirement Planner focuses on income, spending and withdrawals. You can use both as your needs change.
Create an account, then use the guided setup or explore sample scenarios to get familiar with the tools. A beta access code is required during closed beta.
No. Projections and simulations are hypothetical estimates based on your inputs and modeling assumptions. Actual results can differ, and no outcome is guaranteed.
Yes. Explore scenarios with different assumptions, such as retirement timing, spending or withdrawal choices. Compare the results before deciding what fits your goals.
No. NestMint provides educational and informational planning tools, not financial, tax, legal or investment advice. Review important decisions with a qualified professional.
It is a proposed one-time access option for a future launch, not a purchase available during beta. Final features, access duration and purchase protections will be stated before you buy. Current access follows the beta terms (opens in a new tab).
YOUR FUTURE IS WORTH EXPLORING
Free during closed beta · No credit card required
A beta code is required during closed beta.

NestMint Workplace
NestMint Workplace helps employees and retirees plan for today and tomorrow with confidence.
Build a strong financial future with tools to plan, save, and stay on track.
Make informed decisions and create sustainable income in retirement.
Set goals, estimate outcomes, and build a plan that fits your future.
Model retirement income and create a withdrawal strategy you can count on.
Compare options side-by-side to find the strategy that aligns with your goals.
Explore different scenarios to prepare for life’s twists and turns.
Your information is protected with industry-leading security and privacy standards.
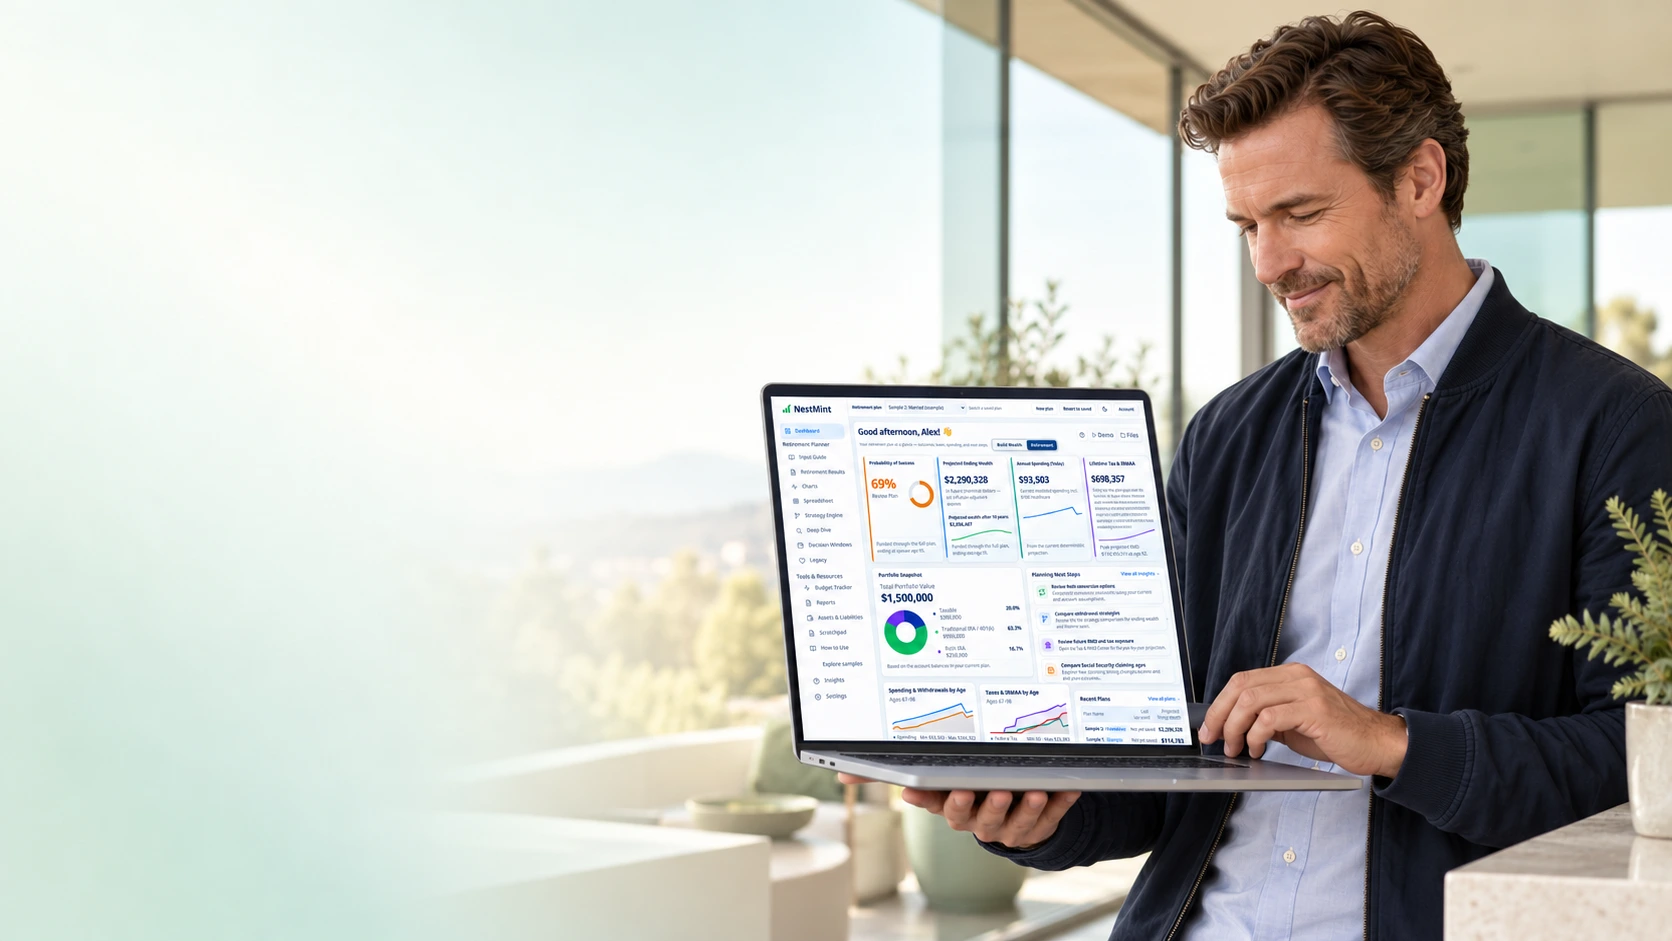
Here’s your financial overview for today.
Open Monte Carlo to calculate a modeled success rate.
Run the Retirement Planner to populate this metric.
From your current plan assumptions.
Medicare IRMAA —
Every tax the plan pays over its horizon, in future dollars, including federal and state income tax. Medicare IRMAA is shown separately, only when Healthcare modeling is on.Run the Retirement Planner to populate this metric.
Run a simulation in the Retirement Planner to populate plan metrics and recommendations.
Open Build Wealth to set your ages, balances, contributions, and target — your growth plan appears here.
See how your savings today can shape your retirement tomorrow.
Enter your balances and contributions in Build Wealth — your projection appears here.
Run the Retirement Planner to activate your plan.
—
No income modeled.
Annual Spending
—in today's dollarsBased on the account balances in your current plan.
Run a retirement simulation to receive plan-specific next steps.
Run a simulation in the Retirement Planner to see projected annual spending by age.
From the current deterministic projection.
Run a simulation in the Retirement Planner to see projected annual taxes by age.
Summed per year from the same projected tax rows as the Lifetime Taxes metric.
Name your plan, review the Input Summary, then adjust any section in the guided planner.
Please enter a plan name.
See how small, consistent savings turn into serious wealth over time.
All sections are filled from your current inputs. You're ready to run the projection.
All changes saved
Brokerage accounts, savings, CDs, etc. — taxed differently from retirement accounts.
Your gross annual employment income. Used to check Roth IRA eligibility, compute employer-match cap (if configured), and project your current-year tax bracket.
Expected yearly raise. Grows the salary your employer match is computed on. Leave blank to use your Annual Increase rate.
Adds your spouse's savings to the household projection. They share your retirement timeline, investment return, annual increase, and salary growth; their salary, contributions, employer match, and starting balance are their own.
Monthly pre-tax 401(k)/IRA contribution.
Monthly Roth contribution.
Included in their Traditional total; remainder is 401(k).
Included in their Roth total; IRA contributions earn no employer match.
Match limited to this percent of their salary (§401(a)(17) pay cap applied to their salary separately).
Seeded as traditional retirement savings.
Money you save each month into a regular taxable brokerage account. Grows in its own bucket — no contribution limit and no employer match.
Included in your Traditional total, not additional savings. The remainder is Traditional 401(k).
Traditional and Roth totals include their IRA portions. Only the 401(k) remainder is eligible for employer match.
Included in your Roth total. The remainder is Roth 401(k). Older plans with no IRA split assume 401(k); review this allocation. Separate dollar caps apply. Confirm compensation, IRA income eligibility, deductibility and mandatory Roth catch-up rules before contributing. Future dollar caps use a 2.5% annual planning estimate, not published future limits.
One rate for raises: it grows your contributions each year and your salary, so the employer-match ceiling below grows with your pay.
Match cap is computed against the Annual Salary in the Compensation section above, indexed each year by your Annual Increase. IRS rules (§401(a)(17)) cap matchable pay at $360,000 (2026, indexed). Leave both fields at 0 if you have no employer match.
Percentage of your contribution the employer matches (e.g. 50% = $0.50 per $1 you contribute).
Maximum % of salary the employer will match on (e.g. 6% means they only match up to 6% of your salary).
Traditional is the default and most common (employer match is pre-tax). Some plans offer Roth-match under SECURE 2.0 — you pay tax on the match amount in the current year but the balance grows tax-free.
Salary grows by your Salary growth rate (or your Annual increase when that is blank); the match cap follows that salary each year, up to the indexed §401(a)(17) pay limit.
Under SECURE 2.0 a high earner’s 401(k) catch-up must be Roth — with no Roth option there is no catch-up.
Used by both Roth tools below — conversion math and contribution-bucket eligibility.
Used to personalize tool suggestions and milestone labels
Set different return rates for different year ranges.
Contributions are assumed to occur evenly throughout the year. Monthly is the most realistic for typical investments.
Your savings goal, as entered in the Goal Simulator.
Projected from current assumptions; not a guarantee.
Traditional + Roth + brokerage
Projected across the savings horizon
Across retirement and taxable accounts
Traditional, Roth, and brokerage balances — with the total — through retirement age.
The estimator preserves the four retirement-account buckets and taxable savings throughout the projection.
Use the estimate to begin spending, tax, healthcare, and withdrawal modeling.
| Timeline | Balances & Contributions | Investment Growth | Projected Outcome | |||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Year | Age | Beg. Balance | Mo. Contrib | Annual Contrib | Empl. Match | Cumul. Contrib + Match | Interest (Yr) | Cumul. Interest | End Balance | % From Growth | Real Balance (today's $) | Mo. Income @ 4% |
See how much free money you're leaving on the table. Enter your employer's match terms.
% of your contribution they match
Max % of salary they'll match on
Track when you'll hit key savings milestones. Based on your current inputs.
How should you split your annual retirement contributions across Roth IRA, Roth 401(k), Traditional 401(k), and Traditional IRA? See your capacity, allocate across the four buckets, and watch how the choice plays out over your time to retirement.
All three scenarios use the same contribution dollars, employer match, and growth rate, so the pre-tax balance is the same. Only the after-tax keep amount changes based on how the money is split between Traditional and Roth. Traditional balances are subject to required minimum distributions beginning at age 73–75; Roth balances are not.
Note: These projections cover retirement accounts only (Traditional & Roth 401(k) and IRA balances). Brokerage and taxable savings are excluded — see the Build Wealth dashboard for your full total including non-retirement accounts.
Important: The lost tax deduction can represent a significant drag on the Roth advantage shown above. If a Traditional contributor were to reinvest those tax savings and let them compound over the full savings horizon, the result would partially offset Roth's edge.
Explore whether converting some traditional retirement savings to Roth before retirement improves your modeled outcome. Conversions add taxable income now; later benefits depend on your assumptions. Use Retirement mode to compare conversions after retirement and their modeled RMD and Medicare effects.
Relevant starting assumptions follow your active Build Wealth plan until you edit them here. These what-if edits do not update the saved plan. Review all assumptions.
A working year, a lower-income gap year and an RMD year can produce different conversion costs. Future income and tax rates are assumptions, not known outcomes.
This Build Wealth tool models conversion years before retirement. The Retirement tools cover later years and additional retirement tax interactions.
Compare converting with not converting. Neither is automatically better.
Federal + state, during conversion window
Federal + state, in retirement
See the cost of waiting. Compare starting today vs. delaying by 1, 3, 5, or 10 years.
Explore where to direct new savings: employer match first, then eligible tax-advantaged accounts and brokerage. Spouse details follow Input Guide when included in your plan. Uses 2026 limits.
Over $150,000 makes catch-up Roth-only. Blank uses current wages as an estimate; enter 0 if appropriate. Your employer Roth availability is set in Input Guide.
If you're 50+, IRS rules let you contribute extra to 401(k) and IRA accounts. See how much more you could save. (2026 limits)
Relevant starting assumptions follow your active Build Wealth plan until you edit them here. These what-if edits do not update the saved plan. Review all assumptions.
Replay your savings plan over the most recent available S&P 500 history, using your selected horizon up to 30 years. Compare historical annual total returns with your assumed-return projection. This is a historical illustration, not a forecast.
| Year | Annual Contribution | Cumulative Contributions | Total Investment Growth | End Balance |
|---|
| Scenario | Updated | Projected at retirement | Target | Status |
|---|
Explore different savings scenarios — solve for the missing variable.
Auto-filled from your Build Wealth plan (Your Savings Today and your monthly contributions) — edit a card to try a what-if; the cards follow the plan again when it changes.
The total balance you want to reach. Seeds the cards below and powers the Savings goal-gap insight.
How much do I need to save each month to reach my goal?
How many years will it take to reach my savings target?
What annual return rate do I need to hit my savings target?
What will my balance be at a specific age given my current plan?
Tell us about you and your household.
This information helps personalize your plan and projections.
Your age as of today.
Pins RMD, 59½ / 70½ and Medicare timing to the right year. Blank = inferred from age.
Age you expect to live to.
Number of years to include in this plan.
Tell us about your household and partner.
Age you expect your spouse / partner to live to.
Portion of pension or income that continues to survivor.
Expected spending as a % of pre-death spending.
Enter your account balances and key assets for the plan.
Fills these account balances from your Build Wealth result. Uncheck to enter your own balances.
Enter your income sources for retirement.
Estimate your Social Security benefit.
Enter the monthly benefit amount used by the retirement engine.
Estimate your spouse / partner's Social Security benefit.
The spousal benefit is set automatically to 50% of your monthly amount.
The engine stores Social Security as a monthly benefit.
Add your defined benefit or other pension income.
Add spouse / partner pension income.
Add recurring employment or other income already supported by the planner.
Separate from your 401(k). Limit $7,500/yr ($8,600 at 50+) in 2026; deductibility phases out at higher incomes when you have a workplace plan.
Add spouse / partner employment income and contributions while working.
Before taxes and deductions.
Enter only the pre-tax workplace-plan contribution while working. Do not include Roth 401(k) or IRA contributions here.
Enter only the Roth portion. This is added to the pre-tax amount, not another way to enter it.
Employer-funded contribution, calculated separately from your spouse's own contributions.
Use both employee fields only when your spouse contributes to both Traditional and Roth 401(k). Do not enter the same contribution twice. NestMint applies a shared employee contribution limit to their combined amount.
Separate from the workplace 401(k), with its own modeled limits and deductibility rules. Enter only the IRA contribution here; it does not earn an employer match.
Organize your retirement spending plan and major cash flow events.
Amounts are in today's dollars and increase with your inflation assumption.
The same amount every year, increased with inflation.
When on, your Budget view's total keeps the annual spending amount in sync.
Define how your spending changes across retirement.
Phases are contiguous — each phase starts where the previous one ends. The last phase covers all remaining years.
Adjust spending when the portfolio crosses your selected guardrails.
Guyton-Klinger style: spending adjusts for inflation, then rises or falls when the withdrawal rate crosses a guardrail, within the floor and ceiling.
Add major planned events that impact your cash flow.
Plan a property sale and, optionally, your next home purchase. Enter each sale here rather than adding it again as a deposit. Net sale proceeds go to your taxable brokerage account.
For each property, select the state where it is physically located, even if you move before selling. Primary-home exclusion eligibility does not determine the property's state. Cross-state tax and credits are planning estimates, not a completed nonresident return.
Enter an expected sale price, or estimate it using today’s value and annual appreciation.
A sale price above $0 overrides the value-and-growth estimate. Blank appreciation uses your plan’s inflation rate.
Cost basis is the original purchase price plus qualifying improvements. Tax on the sale’s gain is paid from the sale proceeds first; any shortfall follows your tax-funding order.
For the home being sold, not its replacement.
Needed only near the one-year boundary.
Gain above any exclusion uses the holding period below. Missing acquisition dates retain long-term treatment; unresolved one-year boundaries use short-term. Confirm special acquisition rules separately.
Checking the saved exclusion eligibility setting…
Leave the purchase price at $0 if you are not buying another home. Purchase year and month default to the sale date.
The purchase price minus the new mortgage is withdrawn in the purchase month and year. Sale proceeds stay invested and available in brokerage, not held in escrow. Include ongoing mortgage payments or rent in Spending.
Enter an expected sale price, or estimate it using today’s value and annual appreciation.
A sale price above $0 overrides the value-and-growth estimate. Blank appreciation uses your plan’s inflation rate.
Cost basis is the original purchase price plus qualifying improvements. Tax on the sale’s gain is paid from the sale proceeds first; any shortfall follows your tax-funding order.
For the home being sold, not its replacement.
Needed only near the one-year boundary.
Gain above any exclusion uses the holding period below. Missing acquisition dates retain long-term treatment; unresolved one-year boundaries use short-term. Confirm special acquisition rules separately.
Checking the saved exclusion eligibility setting…
Leave the purchase price at $0 if you are not buying another home. Purchase year and month default to the sale date.
The purchase price minus the new mortgage is withdrawn in the purchase month and year. Sale proceeds stay invested and available in brokerage, not held in escrow. Include ongoing mortgage payments or rent in Spending.
Full eligibility: confirm the ownership and residence tests, both spouses' residence tests for a joint exclusion, and no disqualifying prior exclusion within two years. No exclusion is applied until confirmed. Entered sales are checked chronologically; another exclusion within 24 months, including the boundary month, is not applied. Exact-date eligibility, partial exclusions and other exceptions require separate tax review. See IRS Publication 523. Not modeled: rental or depreciation history, installment sales and like-kind exchanges. The property state is assumed to follow the federal exclusion.
The existing capital-loss pool is modeled as long-term: it offsets long-term gains first, then short-term gains. Separate short-term carryforwards are not tracked. This is a planning simplification; IRS Publication 550 explains the actual character rules.
Add notes about your spending plan, assumptions, or anything important to remember.
Plan for healthcare costs in retirement.
Salary does not automatically mean you have health insurance. Blank or 0 keeps your entered costs active from today. To exclude costs while covered, enter each person's age when that coverage ends.
These ages suppress modeled healthcare costs before the age entered; they do not estimate payroll premiums. If family coverage ends when either partner retires or dies, enter that year using each person's own age. An age past 65 also delays Medicare: review the coverage type in Deep Dive.
Enter your expected annual healthcare costs by phase.
Estimate Medicare premiums and IRMAA surcharges using prior-year MAGI.
Medicare Advantage user? Set Medigap / Supplemental to $0; an explicit $0 is honored.
Used to estimate income-related monthly adjustment amounts.
We’ll use this history to project IRMAA brackets and surcharges.
Set your market return and volatility assumptions.
Choose how investment returns are modeled in your plan.
Returns compound geometricallyNominal annual return before taxes and withdrawals.
Each account class grows at its own nominal rate. Cash & Other uses its own rate under Other assumptions (0% = held flat).
Phase lengths are fixed, not editable. The main projection counts from its first modeled year; a separate pre-start bridge uses its own year count. Phase rates apply to all accounts together — per-account rates aren't available in this mode. Your Blended / Per-Account choice is kept and applies again when you switch back to Fixed Rate.
Controls annual return swings in Monte Carlo, not the fixed-return projection. This is annual standard deviation, not a guaranteed range or a percentage deducted from your expected return. Higher volatility widens simulated outcomes.
Used in Blended and Variable by Phase modes. Auto follows the expected return; in phase mode it can change from phase to phase.
Per-Account mode uses each account’s own profile. These settings are retained separately from portfolio volatility.
Applies in every returns mode. 0% holds Cash & Other at its entered value; it is spent first and never takes your investment return.
How often returns are compounded. Monthly (12x/year) is the most common default.
Set your tax profile and choose the strategy preferences that shape the plan.
Choose how NestMint estimates federal tax. Your state is modeled separately.
One effective rate on all ordinary income, every year. Your state is still taxed on its own rules.
The one state your plan is taxed in, with either federal method. Moves go in Deep Dive › Change Tax Residency.
Tax brackets and deductions grow at this rate in future years, as the IRS adjusts them for inflation.
The 2026 IRS amount for your filing status, indexed each year. Set automatically; it follows your filing status.
Your yearly itemized deductions (mortgage interest, state and local taxes, charitable gifts) in today’s dollars, indexed each year. Replaces the standard deduction and its age-65+ add-on.
This plan applies no deduction. Choose Standard or Itemized to apply one.
Recommended on. Adds the age-65+ amount to the standard deduction in eligible years (not used when you itemize).
Applies the modeled temporary senior deduction in eligible years, including income limits.
Withdrawals from IRA/401(k) are always taxed as ordinary income. Check additional income types to include in your tax calculation.
Recommended on. NestMint calculates the taxable portion; off treats all benefits as tax-exempt.
Turn off only to model a fully tax-exempt pension. Otherwise tax may be understated.
Enter gross wages. On includes income and employee payroll taxes; off excludes both, but does not disable contributions or create a net-pay mode.
Only the gain portion of a brokerage sale is taxed. Set your starting gain percentage below.
Rates are computed per year from your taxable income — nothing else to set. The bracket preview lives in Tax settings.
Offsets gains first, then ordinary income up to $3,000/yr ($1,500 if Married Filing Separately).
Unrealized gain as a percentage of today’s brokerage balance. Use 0 for no gain or a negative percentage for a loss.
Withdrawals to pay tax can themselves create additional tax.
Turn off to use your planned spending budget instead of taking extra withdrawals for taxes. This leaves less to spend; the reduction appears in Unmet Need.
Choose which accounts fund tax that available income does not cover.
This sets when regular withdrawals are modeled within each year, not your retirement age. Earlier withdrawals leave less money invested during the year, so the timing can change projected growth.
Choose how the engine takes distributions. RMDs are always taken first.
Computed from your birth year under SECURE 2.0.
Move money from Traditional IRA/401(k) to Roth. The converted amount is taxed as ordinary income in the year of conversion, but then grows and withdraws tax-free. Leave amount at $0 to skip.
The amount is a flat nominal figure each year (not indexed). The tax on each conversion is paid like every other tax: from income left after spending, then from accounts in your Tax Funding order. Conversions raise the income Medicare premiums are priced on two years later (IRMAA). Need a year-by-year schedule? Use the Roth Conversion Explorer in the Deep Dive tab.
Harvesting reinvests proceeds and raises tracked cost basis. Harvest Rate caps the amount modeled.
Realizes gains within available federal bracket room. Requires capital-gains tax and Automatic LTCG modeling; no loss harvesting is modeled.
A 0% gains rate does not guarantee zero overall cost. Compare on and off, including Social Security tax and Medicare surcharges.
Share of the available 0% (and, if enabled, 15%) bracket room to use each year — not a share of the balance.
Allows gains in the 15% zone and can increase current tax. Compare the full modeled outcomes.
Recommended on. Skips harvesting while a loss carryforward remains after sales, rather than using it up on harvested gains.
NestMint applies the exception to eligible modeled 401(k) withdrawals based on each person’s separation age. IRA withdrawals are not covered.
Keep workplace-plan money in the 401(k) fields under Accounts. Separation age uses employment End Age, or retirement age when no employment is modeled.
For a confirmed SEPP, disability or other qualifying exception. This is separate from the automatic Rule of 55 calculation.
Applies to both people and all modeled traditional accounts, with no eligibility check. Leave off for mixed or uncertain eligibility; confirm with your plan administrator.
These settings affect after-tax wealth estimates and strategy comparisons, not your annual cash flows or Projected Ending Wealth. Projected Ending Wealth includes taxes paid during the plan, but not a final tax adjustment on the remaining assets. Enabled shared heir filing and income assumptions also feed Legacy’s heir estimates.
Inherited values assets for your heirs. Liquidate values assets for you as the owner.
Used only for Inherited valuation. This manual rate does not set Legacy’s progressive federal tax calculation.
Legacy separately models progressive federal taxes and a payout schedule, so its results can differ. Edits made within Legacy do not change these saved assumptions or strategy rankings.
Review your plan before running the simulation.
All required sections are complete. You're ready to run the simulation.
This takes a few seconds. Your inputs stay editable afterward.
Model income, withdrawals, taxes, and spending — know exactly how long your money lasts.
Sets your RMD start age, 59½ and 70½ dates, and Medicare/SS timing. Blank = inferred from your age.
Keep workplace-plan money here rather than under Traditional IRA if you may retire between 55 and 59½: the Rule of 55 waives the 10% early-withdrawal tax on 401(k) draws only, and NestMint applies it to this balance automatically.
Enter the benefit amount for the age you plan to claim. Find yours at ssa.gov/myaccount or on your annual SSA statement.
62 = reduced (~70%), 67 = full, 70 = max (~124%)
Annual cost-of-living adjustment. SSA historical avg ~2.5%. Set to 0 to model flat benefits.
The last age this pension pays. Set to life expectancy for a lifetime pension.
Age range for employment income. 0 means “not set”: a 0 Start Age begins at your current age; a 0 End Age follows your planned retirement age.
Blank = grows with your inflation rate. Plans saved before this field existed keep flat wages (0).
Deposits to your IRA/401(k) pool each working year and reduces taxable wages; IRS deferral limits (incl. 50+ / 60–63 catch-up) apply.
After-tax; deposits to your Roth pool. Shares the same IRS deferral limit.
Dollar-for-dollar up to this share of what you defer (enter 3 for "100% of the first 3%"). Goes to your IRA/401(k) pool.
Deductible contributions to your Traditional IRA while you have earned income: capped at the IRS IRA limit (2026: $7,500; $8,600 at 50+) and, when you are covered by a workplace plan, at the deductible amount for your income.
Adjusted annually for inflation.
Define your own spending phases. Set the end year for each phase and the annual amount. The last phase covers all remaining years. Each phase amount is in the dollars of the year that phase begins (it then inflates within the phase): a later phase entered as $59,500 is $59,500 in that future year, not today's dollars.
Spending adjusts dynamically with the portfolio's withdrawal rate (Guyton-Klinger). Set an initial spending amount and the guardrail bands around your initial withdrawal rate.
Each year the portfolio withdrawal rate — last year's actual draws (spending, healthcare and taxes net of Social Security, pensions and wages) over the opening balance — is compared with the bands around your initial rate: below the prosperity band spending rises by the increase amount; above the capital-preservation band it is cut by the decrease amount (not in the plan's last 15 years). The inflation raise is skipped after a losing year while the rate is above the initial rate. Floor and ceiling bound the result.
Draw from brokerage accounts first, then traditional IRA, then Roth. RMDs are always taken.
Your required minimum distribution is cash you must take. Spend first uses it toward the year’s spending, then toward that year’s tax bill, before any other account is drawn, in every order; only what is left is reinvested into brokerage. Reinvest deposits it into brokerage and funds spending from the chosen order as if it were not there — under Brokerage First that sells appreciated shares you did not need to sell.
When withdrawals are taken each year. Affects how much growth applies before money leaves the account. "Equal Throughout" models monthly withdrawals spread across the year (the same as a mid-year withdrawal on average).
One-time or multi-year extra withdrawals added on top of regular spending. Set From and To to the same year for a single-year withdrawal. Month controls when in the year the withdrawal occurs (affects growth).
One-time lump-sum deposits of after-tax money (e.g., inheritance, life insurance). For a home sale, use Home Sale below. Funds are added to your taxable account balance. Month controls when in the year the deposit occurs (affects growth).
Selling your home, a second home or other property? Enter it here, not as a deposit: enter today's value and a growth rate, or simply the price you expect in the sale year (a sale price, when entered, is used as is). The net proceeds are added to your taxable account, and the gain is taxed in the sale year after the home-sale exclusion ($250,000, or $500,000 married filing jointly, for an eligible primary home after you confirm full exclusion eligibility). The default state estimate follows residence in the sale year, with confirmed other-state loss-origin add-backs. Use Advanced to enter a final gain and rate for property-source or other adjustments; this is not a state return or credit calculation. Not modeled: rental or depreciation history, partial exclusions, installment sales and like-kind exchanges.
Enter an expected sale price, or estimate it using today’s value and annual appreciation.
A sale price above $0 overrides the value-and-growth estimate. Blank appreciation uses your plan’s inflation rate.
Cost basis is the original purchase price plus qualifying improvements. Tax on the sale’s gain is paid from the sale proceeds first; any shortfall follows your tax-funding order.
For the home being sold, not its replacement.
Needed only near the one-year boundary.
Gain above any exclusion uses the holding period below. Missing acquisition dates retain long-term treatment; unresolved one-year boundaries use short-term. Confirm special acquisition rules separately.
Checking the saved exclusion eligibility setting…
Leave the purchase price at $0 if you are not buying another home. Purchase year and month default to the sale date.
The purchase price minus the new mortgage is withdrawn in the purchase month and year. Sale proceeds stay invested and available in brokerage, not held in escrow. Include ongoing mortgage payments or rent in Spending.
Enter an expected sale price, or estimate it using today’s value and annual appreciation.
A sale price above $0 overrides the value-and-growth estimate. Blank appreciation uses your plan’s inflation rate.
Cost basis is the original purchase price plus qualifying improvements. Tax on the sale’s gain is paid from the sale proceeds first; any shortfall follows your tax-funding order.
For the home being sold, not its replacement.
Needed only near the one-year boundary.
Gain above any exclusion uses the holding period below. Missing acquisition dates retain long-term treatment; unresolved one-year boundaries use short-term. Confirm special acquisition rules separately.
Checking the saved exclusion eligibility setting…
Leave the purchase price at $0 if you are not buying another home. Purchase year and month default to the sale date.
The purchase price minus the new mortgage is withdrawn in the purchase month and year. Sale proceeds stay invested and available in brokerage, not held in escrow. Include ongoing mortgage payments or rent in Spending.
Confirm full exclusion eligibility: ownership and residence requirements, both spouses' residence tests for a joint exclusion, and no disqualifying prior exclusion within two years. No exclusion is applied until confirmed. Entered sales are checked chronologically; another exclusion within 24 months, including the boundary month, is not applied. Exact-date eligibility, partial exclusions and other exceptions require separate tax review. See IRS Publication 523.
The existing capital-loss pool is modeled as long-term: it offsets long-term gains first, then short-term gains. Separate short-term carryforwards are not tracked. This is a planning simplification; IRS Publication 550 explains the actual character rules.
Move money from Traditional IRA/401(k) to Roth. The converted amount is taxed as ordinary income in the year of conversion, but then grows and withdraws tax-free. Leave amount at $0 to skip.
Tip: Use the Roth Explorer strategy tool to find the optimal conversion amount, then enter it here to include it in your main projection.
Adds Medicare Part B, Part D, Medigap, IRMAA surcharges, and out-of-pocket costs to your annual spending. Costs grow at the healthcare inflation rate. IRMAA surcharges are based on your MAGI from 2 years prior (e.g., your 2026 Medicare premiums are determined by your 2024 income). For the first two years of your projection, NestMint uses positive amounts entered in the Prior Year MAGI fields below. Blank or $0 entries use a planning estimate instead and may produce IRMAA surcharges; they do not mean no surcharge. Enter your actual prior-year MAGI when available.
Set different return rates for different retirement phases.
Withdrawals from IRA/401k are always taxed as ordinary income. Check additional income types to include in your tax calculation.
Auto-set by filing status (2026 IRS amount).
$1,650/person MFJ, $2,050 single (2026). Only applies with standard deduction.
Up to $6,000/person ($12,000 MFJ). Phases out at MAGI > $75K single / $150K MFJ. Applies to both standard and itemized filers.
These settings affect after-tax wealth estimates and strategy comparisons, not your annual cash flows or Projected Ending Wealth. Projected Ending Wealth includes taxes paid during the plan, but not a final tax adjustment on the remaining assets. Enabled shared heir filing and income assumptions also feed Legacy’s heir estimates.
When enabled, these saved assumptions set the inherited lens's state-tax income stack and seed Legacy's filing and income fields. The federal heir tax rate above remains your manual assumption. Legacy separately models progressive federal taxes and a payout schedule, so its total can differ. Local edits in Legacy do not change these saved assumptions. When disabled, existing plan valuation behavior is retained.
How ending wealth is valued after tax in the Strategy Engine and Roth Explorer. Inherited: the traditional IRA is taxed at your heirs’ marginal rate (the standard adult non-spouse assumption uses a ten-year payout; exceptions can apply); brokerage gains step up at death; Roth is tax-free. Liquidate: you sell everything — brokerage gains at the 0/15/20% capital-gains rates plus NIIT and state, the IRA drained over ten years on top of your final-year income. One method values every strategy.
Determines tax brackets, standard deduction amounts, and long-term capital gains (LTCG) thresholds.
Annual inflation adjustment for tax brackets, standard deduction, and long-term capital gains (LTCG) thresholds. Set to 0% to use fixed 2026 levels. Historical IRS adjustments average ~2-3%.
Uses 2026 IRS tax brackets. Federal tax is computed progressively on taxable income after deductions.
How taxes are paid. Available income, already-withdrawn RMD cash and a home sale’s own proceeds pay tax first. With Pay taxes from accounts on, extra withdrawals follow the selected order and can create additional tax. With it off, remaining tax reduces your spending budget instead. Spending reductions and unpaid tax appear in Unmet Need.
Turn off to pay taxes within your planned budget instead of withdrawing additional money. This reduces spending available and is shown in Unmet Need. Available income, RMD cash and a home sale’s own proceeds are still used first.
Taxes paid from brokerage first — IRA compounds without tax-funding draws.
Configure long-term capital gains tax rate, brokerage gain estimates, auto-harvesting, and loss carryforward.
Key outcomes from your current retirement plan.
Annual averages, in future dollars. Every year in each period is included.
Spending includes modeled healthcare, after other income. Tax funding is from accounts, not the entire tax bill. Special withdrawals show the funded amount. Reinvested RMDs stay invested; they are not spending.
No simulation has been run yet for this plan. Run your first simulation to see projected outcomes, tax totals, RMD and IRMAA figures, and your current plan summary.
A quick comparison of withdrawal approaches under your current inputs. Open Strategy Engine for the full strategy analysis.
Total portfolio value across all strategies.
Total portfolio value across all strategies — no percentile band.
Income = Social Security, pension, and employment. Spending = the plan’s spending need.
Distribution of accounts over time. Based on account balances.
Includes SS, pensions, withdrawals, and conversions.
Choose how strategies are ranked and run the engine using the assumptions in your current plan.
Tests combinations of withdrawal order, Social Security timing, and Roth conversion schedules — every candidate is a full plan simulation under your current assumptions.
Each finalist is then stress-tested across 2,000 seeded market paths — the same paths for every strategy, and the same count the dashboard’s Monte Carlo runs — and ranked by the outcome lens you choose.
See how different Roth conversion strategies would affect your lifetime taxes, RMDs, and ending net worth. The Explorer runs your full retirement simulation with and without conversions and compares the results. Tax on conversions is fully included — the converted amount is added to your taxable income each year, taxed at your federal + state rate, and reflected in all totals. A positive result means the upfront tax cost is outweighed by tax-free growth and lower future RMDs. A negative result means conversion costs more than it saves in your scenario — both outcomes are possible and the Explorer shows you which applies.
The core question is your tax rate today vs. your tax rate later.
Converting makes sense when your marginal rate during the conversion window is lower than the rate you'd pay on future RMDs. In that case, you prepay tax at a discount and all future growth is tax-free. The benefit compounds over 20–30 years and can be substantial.
Converting hurts when your current marginal rate equals or exceeds your expected future RMD rate. You'd be paying more tax today to avoid less tax later — a net loss that also compounds over time.
What drives the future RMD rate? Once large income sources like a pension or employment income end, your taxable income often drops significantly. Social Security and RMDs alone may put you in a lower bracket than you're in today — especially in the years before RMDs begin. That's typically where the opportunity lies.
What raises your current conversion rate? Pension income, employment income, and Social Security all stack on top of any conversion amount, pushing the marginal rate on the converted dollars higher. If your income is already high, conversions may land in the 24–35% federal bracket before state tax is added.
The Explorer below runs both scenarios for you and shows the actual dollar impact. Check the tax rate column to see what rate each strategy is effectively paying — and compare that to your projected RMD-year rate.
There is no IRS limit on how much you can convert per year. However, bigger is not always better. Key trade-offs:
The sweet spot — if one exists — is typically converting enough to fill your current tax bracket without jumping to the next one, or staying below the first IRMAA threshold. For some users, the optimal conversion amount is zero: if your income during the conversion window already exceeds your projected RMD rate, conversion increases lifetime taxes rather than reducing them. The Explorer's tax rate column shows the effective rate you'd pay on each strategy so you can compare it directly to your expected future rate.
These constraints apply only to "Compare Scenarios". IRMAA cap keeps MAGI below the first surcharge tier. Max bracket limits conversions. Min liquidity ensures brokerage stays above this floor.
Adjust assumptions and stress-test your retirement plan. Change return rates, life expectancy, inflation, SS timing, and spending to see how each affects your outcome.
How would your plan survive a major market crash? Pick a scenario, choose when the crash hits, and see the impact — including the recovery rally.
Run your retirement plan through 2,000 seeded market paths sampling annual returns around your expected return. Instead of one straight-line projection, see the modeled success rate and the range of possible outcomes. Same inputs always produce the same results.
Explore how moving between states could affect taxes and Projected Ending Wealth. Compare your move timeline with staying in your current state, using the same plan assumptions.
Starting state: (set in Input Guide › Taxes › State Income Tax)
Your starting state applies until the first move. Use the first projection year to compare the entire plan in a different state.
Adding or removing a move updates your working plan. Save your plan explicitly to keep the change.
Your effective tax rate in retirement, the tax brackets you fill, and opportunities to manage taxes on withdrawals and investment gains.
Your plan tracks one cost basis for your brokerage, seeded from Starting Gain %. This view follows that basis, the gain or loss on investment sales, and harvesting over time. Capital-gains tax is shown separately as an all-source total, including any taxable long-term home-sale gains.
Find your unrealized gain on your brokerage statement. This is the same input as Input Guide › Taxes & Strategy › Starting Gain %. Zero means no starting embedded gain; a negative percentage means the account is below cost. This edits your plan, not a separate estimate. Save explicitly to keep changes.
Comprehensive risk analysis with Monte Carlo success probability, tax burden, RMD exposure, and 5 more risk factors. Adjust the scenario sliders below to stress-test how changing assumptions affects your risk profile — without changing your main inputs.
What if you retired 30 years ago with your current balances? This shows how actual S&P 500 returns — including the dot-com crash, 2008 financial crisis, and COVID — would have affected your portfolio.
Compare different withdrawal sequences to see which order of drawing from your accounts preserves wealth the longest. Your current withdrawal order setting from the inputs above is highlighted.
Review your projected Required Minimum Distribution schedule starting at your RMD age (73 or 75, set by your birth year), based on your projected IRA/401(k) balance at that age (not your current balance). RMD amounts are calculated using the IRS Uniform Lifetime Table. See how RMDs grow over time, their tax impact, and strategies to reduce them through early withdrawals or Roth conversions.
Evaluate whether your planned spending is sustainable. See your effective withdrawal rate, how it compares to common benchmarks, and when adjustments might be needed.
Model Medicare premiums, IRMAA surcharges, Medigap supplements, and out-of-pocket costs through retirement. Healthcare inflation (~5.8%) outpaces general inflation — see how it compounds and what share of your spending goes to medical costs.
Compare claiming Social Security at different ages to see how each option affects your lifetime benefits, ending balance, and total income. Includes break-even analysis and COLA growth projections.
Get age-appropriate asset allocation suggestions for your retirement accounts. See how shifting between stocks, bonds, and cash affects your projected outcomes over time.
See a visual timeline of key retirement milestones — from Social Security eligibility and Medicare enrollment to RMD start dates, spending phase changes, and projected fund depletion. Understand what happens at each stage.
A year-by-year breakdown of the first 10 retirement years: where your taxable income comes from, how the tax breaks down by type, and which account funded each tax dollar. Useful for spotting bracket-creep and brokerage-drain patterns.
Inspect the year-by-year simulation data, export to CSV for external verification, and review engine diagnostics. Useful for validating results against your own spreadsheet or tax preparer’s projections.
Assumptions changed since this projection — press Run to refresh these windows.
Shared axis; per-person events where timing differs; household opportunities appear once.
Events are grouped by person, followed by household opportunities. The axis gives the next ten years most of the width and compresses the years after. Detailed windows are below.
Household opportunity
From 2026 through 2033. Ends when Social Security begins.
Per person
Open since 2026. Income from this year on sets Medicare premiums two years later (the lookback); the band stays open for life. Opens in 2026, two years before Medicare: from then on, each year’s income sets Medicare premiums two years later (the lookback), for life.
Per person · dated event
First RMD year: 2038. May defer first distribution to April 1, 2039; deferral bunches two RMDs into that tax year. RMDs are under way; the April 1 deferral applied only to the first year.
Per person · ages 62–70
Claim window: 2025 – 2033. Each year of delay raises the monthly benefit for life. Claiming before full retirement age while still working can temporarily withhold benefits (earnings test). The claim window has passed; the plan models benefits from the claim age below.
Per person
Open since 2026. Income from this year on sets Medicare premiums two years later (the lookback); the band stays open for life. Opens in 2026, two years before Medicare: from then on, each year’s income sets Medicare premiums two years later (the lookback), for life.
Per person · dated event
First RMD year: 2038. May defer first distribution to April 1, 2039; deferral bunches two RMDs into that tax year. RMDs are under way; the April 1 deferral applied only to the first year.
Per person · ages 62–70
Claim window: 2025 – 2033. Each year of delay raises the monthly benefit for life. Claiming before full retirement age while still working can temporarily withhold benefits (earnings test). The claim window has passed; the plan models benefits from the claim age below.
Household exposure
MFJ brackets last only while you both do. This is an exposure, not an open/closed window, and it has no close date.
Household exposure
Your state taxes Social Security above an income line. Roth conversions and large withdrawals count toward it — crossing can add state tax on your benefits.
Household window
The subsidy cliff is back: marketplace premium credits now end entirely at the federal poverty-line threshold. Conversions, withdrawals, and untaxed Social Security all count toward it — until Medicare begins.
Temporary statutory window
Eligible window: 2028 – 2028. Not applicable to your plan. OBBBA is the 2025 federal tax law (the “One Big Beautiful Bill Act”). It added an extra $6,000 standard deduction per person aged 65+ for tax years 2025–2028, phasing out above $75,000 of income ($150,000 married). The window is the years you or your spouse are 65+ while it is on the books; a dash means nobody in the plan is 65 before it sunsets.
Reached 2023.Reaches 2023. Penalty-free access to retirement accounts.
Reached 2023.Reaches 2023. Penalty-free access to your spouse’s retirement accounts.
Modeled transition begins 2028.Modeled transition began 2028.
—
—
Modeled transition begins 2028.Modeled transition began 2028.
—
—
Eligible around 2034.Eligible since 2034, for life. Not modeled in the projection.
Eligible around 2034.Eligible since 2034, for life. Not modeled in the projection.
Temporary eligibility window: 2025–2028 (tax years).Not applicable to your plan: it sunsets before anyone in the plan turns 65.
Projections are based on your plan assumptions and current law. Estimates only — not tax or investment advice.
| Timeline | Portfolio | Income | RMDs & IRAs | Spending & Healthcare | Withdrawals | Taxable Income & Gains | Taxes | Cash Flows | Contributions | End-of-Year Balances | |||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Age | Year | Beg Bal | Growth ⓘ | SS Inc | Pension | Employ | RMD ⓘ | Exc RMD | IRA/401(k) Beg ⓘ | Spouse IRA Beg ⓘ | Spend Need ⓘ | HC Base | HC IRMAA | Spend W/D ⓘ | IRA → Spend ⓘ | Spcl W/D | Ord Tax Inc | Deduction ⓘ | Est Tax Inc | Brkt Room | Brkt Used | Roth Conv | Cap Gain | Cap L Used | Net Gain | Loss C/O | Base Fed | Base St | CG Tax | G-U Tax | Oth Tax | Tot Tax | Spend W/D | Spcl W/D | Tax W/D | Tot W/D | Spcl Dep ⓘ | Contrib ⓘ | IRA/401k | Roth | Brokerage | Cash ⓘ | End Bal |
Presentation: Spend Need is shown accounting-style — red parentheses denote a cash outflow. The underlying value is the plan’s spending target for the year; the CSV export carries the plain number.
Withdrawals: Spend W/D = withdrawal for living expenses. Spcl W/D = special withdrawal (also taxed). Tax W/D = withdrawal to fund taxes. Tot W/D = Spend W/D + Spcl W/D + Tax W/D. Spend W/D appears twice: once next to Spend Need (includes Spcl W/D) and again in the withdrawal math section (excludes Spcl W/D, shown separately).
Income & Tax: Ord Tax Inc = ordinary taxable income before deductions. Deduction = standard or custom deduction applied. Est Tax Inc = Ord Tax Inc − Deduction (estimated taxable income, ties to Tax Bracket Management). Roth Conv = amount converted from Traditional to Roth (included in Ord Tax Inc). Note: If the Enhanced Senior Deduction (One Big Beautiful Bill, 2025–2028) is enabled, you will see a step-down in the Deduction column in the first year after it expires — this is correct and reflects the provision's scheduled end date.
Bracket Fill (Tax-Smart): Brkt Room = how much IRA withdrawal room exists before hitting the target bracket ceiling (ceiling − base income). Brkt Used = actual IRA withdrawal taken to fill the bracket; this amount is included in Ord Tax Inc and taxed accordingly. If RMD exceeds the room, the excess is reinvested into brokerage. These columns are zero when not using Tax-Smart withdrawal order. Click any cell for the full breakdown.
Capital Gains: Cap Gain includes brokerage gains, harvested gains and home-sale gains after any exclusion. Cap L Used shows loss offsets; Net Gain shows taxable gains after offsets. Click Net Gain to see the short-term home-sale and long-term portions. Loss C/O is the remaining loss carryforward.
Tax Computation: Net short-term home-sale gains are included in Ord Tax Inc and ordinary federal tax. CG Tax applies to the long-term portion using the applicable deduction and rate brackets, not to all Net Gain. Base St includes the modeled state tax. G-U Tax is additional tax from funding taxes via IRA; Oth Tax includes NIIT, payroll tax and penalties. Tot Tax = Base Fed + Base St + CG Tax + G-U Tax + Oth Tax. The gain is not added to cash income again; sale proceeds already account for the cash received.
Eight focused steps. Your answers update the existing Build Wealth automatically.
Add assets and debts outside your retirement plan to see your complete financial picture.
Retirement and investment accounts already entered in NestMint are included automatically.
Do not enter those accounts again here.
Only assets not already included in your NestMint savings or retirement accounts.
Enter current balances, not original loan amounts.
Optional. These entries calculate your broader net worth and do not change Build Wealth or Retirement Planner projections.
Save to create your Asset & Liability Overview. You can update these values at any time.
A broader net-worth view kept separate from the assets used in your retirement projection.
Not yet saved
Save future updates to build your net-worth history.
Track every dollar in and out — whether it's a paycheck or a pension.
Monthly expenses by category
Review, export, and share the analysis already produced by your planning tools.
Headline projections, detailed annual results, and complete plan exports.
A shareable summary of assumptions, balances, income, spending, taxes, and projected outcomes.
Export the complete annual projection for further review in a spreadsheet.
Open the current plan's charts, account balances, taxes, withdrawals, and annual spreadsheet.
Explore factual differences among withdrawal approaches and inspect every calculation.
Compare withdrawal strategies against the same retirement-plan assumptions.
Open all detailed sections, including accounts, taxes, cash flow, healthcare, RMDs, Monte Carlo, and legacy analysis.
Review conversion comparisons, projected taxes, future RMDs, and ending wealth.
Generate focused reports from the other areas of your financial workspace.
Export the current savings projection, assumptions, and accumulation results.
Export income, expenses, savings rate, and multi-year budget projections.
Open beneficiary, estate-transfer, tax, and inheritance projections based on the current plan.
All your saved work in one place. Click any item to open it.
No saved scenarios yet
No saved scenarios yet
No saved scenarios yet
No other data
Your date of birth and state feed your plan: state drives the state-tax model, and ages drive projections.


